Soft-tissue reconstruction solutions
OviTex and OviTex PRS reinforced tissue matrices
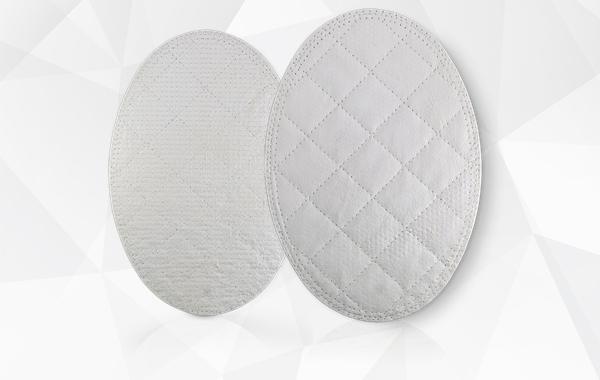
OviTex
Used in hernia repair and abdominal wall reconstruction
OviTex PRS
Used in plastic and reconstructive surgery
$1.8B
The company’s estimate of the total addressable annual U.S. market for OviTex (10-K); not a revenue forecast.
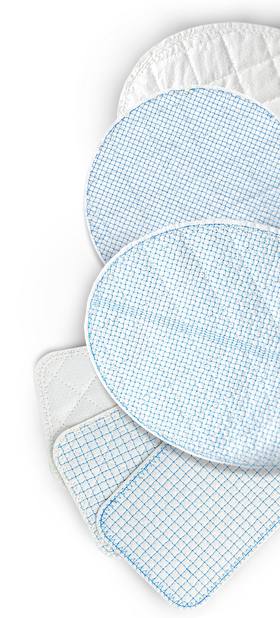
How OviTex
is made
Layers of ovine (sheep) rumen tissue, stitched with polymer thread
- OviTex Core (four layers), 1S (six) and 2S (eight).
- Polymer is about 5% of OviTex Core, 1S and 2S by mass (company, 10-K).
- Depending on configuration, the company says its polymer content is about 75% less than the most widely implanted permanent synthetic mesh (10-K).
Revenue
$38.4M
H1 2026 revenue, down 1% from $38.7M; unaudited (10-Q)
$80.3M
2025 revenue, up 16% from $69.3M (10-K)
Q2 revenue was down 4%. The 10-Q cites lower OviTex PRS sales and U.S. price/mix pressure (H1 revenue by line, Note 4: PRS down 15%, OviTex up 5%).
H1 2026 net loss was $23.5M, up 11% from $21.2M (10-Q).
2026 revenue guidance was withdrawn Aug 10 (8-K).
 NASDAQ: TELA
Substantial going-concern
doubt · 10-Q, Aug 11
Forward-looking statements (e.g., Q3 timing, Liora’s prospects) are uncertain; actual results may differ materially. Not an offer to sell or buy securities, or investment advice. 2026 figures (H1, Q2, Jun 30 balances) are unaudited. 10-Q: substantial doubt about going concern. Risks: loan covenant default; more financing and dilution; reverse split approved, none intended now; CEO/CFO changes; OviTex made by one contract manufacturer. Figures are from SEC filings through Oct 8; Q3 results (expected early November) may change them. See Risk Factors in TELA Bio’s SEC filings.